
Paying for a Lower Mortgage Rate? Florida Calculator Shows the Cost Before Buyers Commit
Mortgage Expert’s calculator helps Florida homebuyers compare mortgage options with and without discount points.
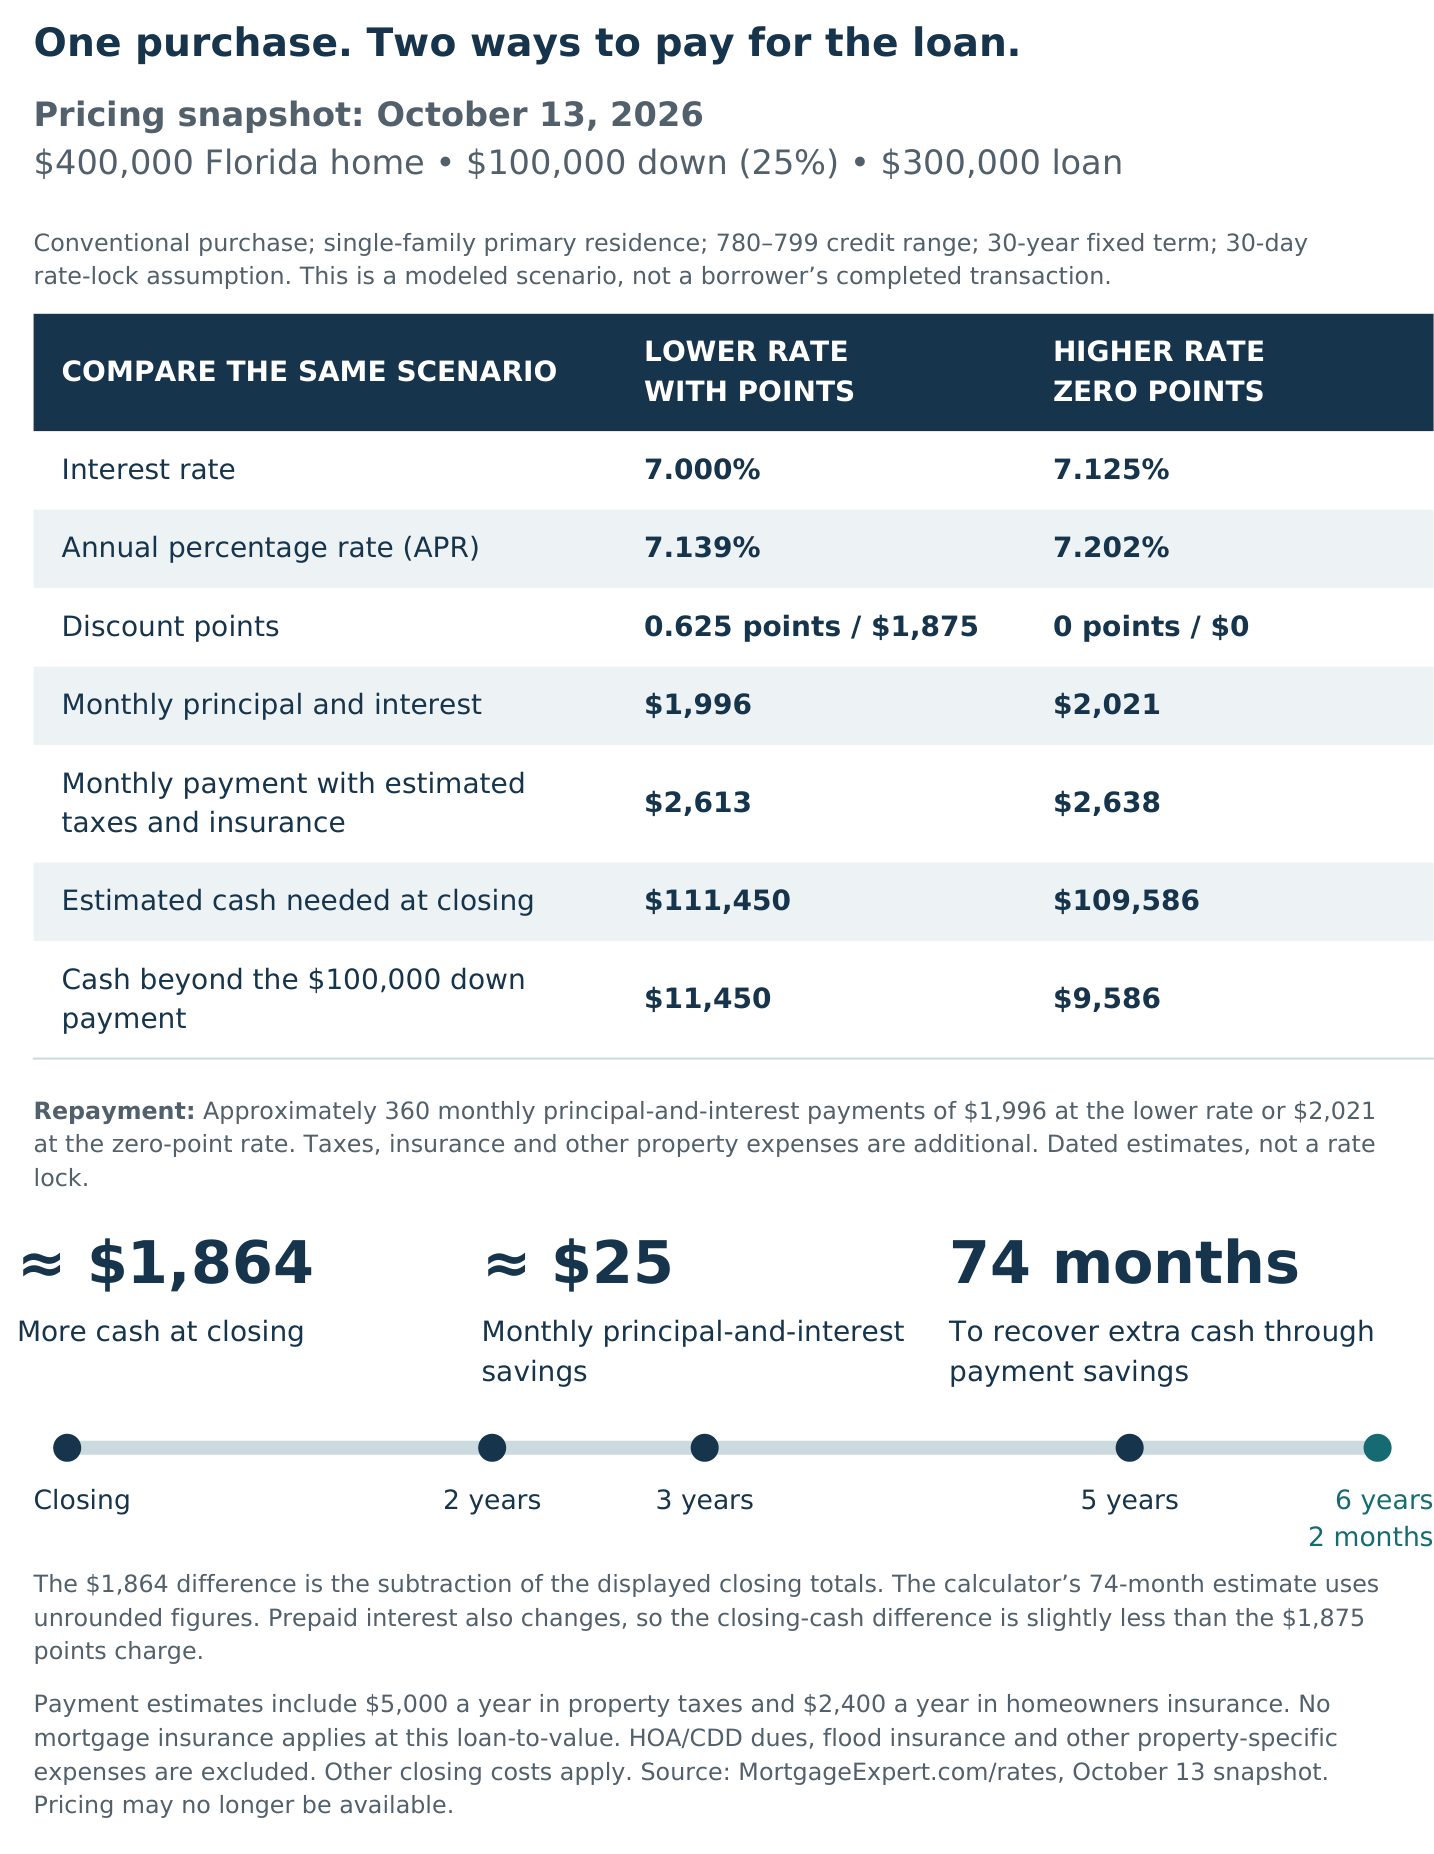
October 13, 2026 pricing snapshot: the same $300,000 Florida loan with points or zero points. Dated planning estimates; pricing may no longer be available.
Mortgage Expert helps buyers compare points, payments and estimated cash to close without entering contact information.
ORLANDO, FL, UNITED STATES, October 14, 2026 /EINPresswire.com/ -- A lower mortgage rate can look like an easy win. But if getting it means paying more at closing, how long will the smaller monthly payment take to repay that extra cash?In a Florida purchase scenario displayed by Mortgage Expert on October 13, 2026, the answer was about six years and two months. That does not make the lower rate a bad choice for every buyer. It shows why the rate alone is not enough to decide.
Shahram Sondi, a licensed mortgage loan originator and owner of Orlando-based mortgage brokerage Mortgage Expert, developed the calculator so buyers can explore that tradeoff before speaking with a loan officer. No name, email address, phone number or credit pull is required to use the calculator.
Freddie Mac's October 8 survey put the national average 30-year fixed mortgage rate at 7.40%, up from 7.28% a week earlier. That is market context, not an individual quote. For buyers balancing a down payment, moving expenses and emergency savings, cash spent obtaining a lower rate is unavailable for something else.
A STARTING POINT FOR SHOPPING
Buyers can adjust purchase price, down payment and credit-score range. The calculator shows selected rates and APRs, points, estimated payments, closing costs, prepaids, escrow funding and cash needed at closing. Tax, insurance and HOA assumptions can be adjusted. It provides a comparison baseline. Additional rates and products may be available after a fuller review; the calculator does not determine eligibility.
“I may have a very competitive offer for one scenario, and another lender may be more competitive for a different one,” Sondi said. “I'm not claiming to have the best rate for every borrower. I'm putting the numbers out there so people can understand their options and shop.”
ONE PURCHASE, TWO OPTIONS
The October 13, 2026 snapshot assumes a $400,000 Florida single-family primary home, $100,000 down (25%), a $300,000 conventional loan, 780–799 credit, a 30-year fixed term and a 30-day lock assumption. It is a modeled scenario, not a completed borrower transaction.
• Lower rate: 7.000% interest, 7.139% APR, 0.625 points ($1,875). Approximately 360 monthly principal-and-interest payments of $1,996. Estimated cash to close: $111,450.
• Zero points: 7.125% interest, 7.202% APR, no discount points. Approximately 360 monthly principal-and-interest payments of $2,021. Estimated cash to close: $109,586.
Taxes, insurance and other property expenses are additional. Including assumed annual taxes of $5,000 and homeowners insurance of $2,400, estimated monthly payments were $2,613 and $2,638, respectively. No mortgage insurance applies at this loan-to-value; HOA/CDD dues and flood insurance are excluded. Other closing costs apply.
The lower rate required about $1,864 more cash based on the displayed totals and saved approximately $25.25 monthly in principal and interest. The calculator's simple payback was 74 months, using unrounded figures. Prepaid interest also changes, explaining why the cash difference is less than the points charge.
WHEN POINTS MAKE SENSE
One discount point equals 1% of the loan amount. The Consumer Financial Protection Bureau explains that the rate reduction varies by lender, loan type and market conditions.
“Sometimes paying for the lower rate makes sense. Sometimes keeping the cash makes more sense,” Sondi said. “I want buyers to see the tradeoff instead of assuming the smallest rate is automatically the best deal.”
Keeping the mortgage longer gives payment savings more time to recover the extra cash. Selling or refinancing sooner may prevent that recovery. The simple calculation excludes remaining loan-balance differences, tax effects and what the cash could earn elsewhere. The lower-rate loan pays down principal somewhat faster. Future refinancing is not guaranteed.
COMPARE THE LOAN BEFORE THE LOGO
“If you're shopping for a Toyota, compare the same model, year and trim, then look at the full price,” Sondi said. “With a mortgage, match the loan amount, program, term and lock period before comparing the rate and fees. A familiar logo or a Super Bowl commercial doesn't tell you who has the better offer for your situation.”
Conforming mortgages follow eligibility standards used by Fannie Mae or Freddie Mac. Lender requirements, fees, pricing and service can still differ. Smaller companies may compete through lower overhead or leaner margins, but size alone does not establish the better offer. Communication and closing reliability also matter.
The down payment is only part of the cash required. In the lower-rate example, other modeled items added $11,450. Keep tax and insurance assumptions consistent when shopping: lower estimates do not necessarily mean lower lender charges. Compare multiple offers and formal Loan Estimates, including fees and lender credits.
“Use the information and shop around,” Sondi said. “If you're buying in Florida and want a second opinion, I'm happy to look at your deal. My goal is to give you clear information, put competitive options in front of you and earn your business.”
Try your own scenario in the mortgage rate calculator: https://mortgageexpert.com/rates/#rate-finder
Read the full guide and view the side-by-side comparison: https://mortgageexpert.com/mortgage-market-updates/should-you-pay-mortgage-points-florida/
Pricing is normally refreshed once each business day; the effective date is displayed. It is not a streaming market feed. Results are estimates, not approvals, official Loan Estimates, commitments to lend or rate locks. Final terms depend on a complete application, verified borrower and property information, program eligibility, underwriting and pricing available when locked. Not all applicants qualify. Zero points does not mean zero closing costs. Dated pricing may no longer be available.
ABOUT SHAHRAM SONDI AND MORTGAGE EXPERT
Sondi (NMLS 186790) is a licensed mortgage loan originator, Certified Mortgage Advisor™ and licensed Florida real estate broker who has originated mortgages since 2001. He has appeared on multiple television news outlets, most recently WESH 2 News discussing rising mortgage rates. Appearances do not imply endorsement of the calculator.
Mortgage Expert, Inc. (NMLS 2412313; Florida license MBR5733) is a Florida-licensed mortgage broker, not a lender. Equal Housing Opportunity. Not affiliated with or endorsed by HUD, FHA, VA or any government agency.
Shahram sondi
Mortgage Expert
+1 407-906-6414
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
